Most people buying a flat in Kolkata use a home loan, so the questions come in a fixed order: how much will the bank lend, how much do I need to pay myself, and what will the EMI be? This guide answers all three for flats priced from ₹30 lakh to ₹60 lakh, with every figure worked out below so you can check it. For current interest rates after the RBI’s October 2026 hike, see our guide to home loan interest rates in Kolkata.
Looking for a specific size or budget? Filter all flats in Kestopur by BHK and price.
How much home loan can you get?
The RBI limits how much of a property’s value a lender can finance, called the loan-to-value (LTV) ratio. The limits depend on the size of the loan: up to 90% of the property value for loans up to ₹30 lakh, up to 80% for loans from ₹30 lakh to ₹75 lakh, and up to 75% for larger loans. In practice, the maximum loan on a ₹32 lakh flat is ₹28.8 lakh, because a loan up to ₹30 lakh can be 90% of the value. Lenders can offer less than the maximum, depending on your income and credit history, and the maximum loan term is 30 years.
How much cash do you need upfront?
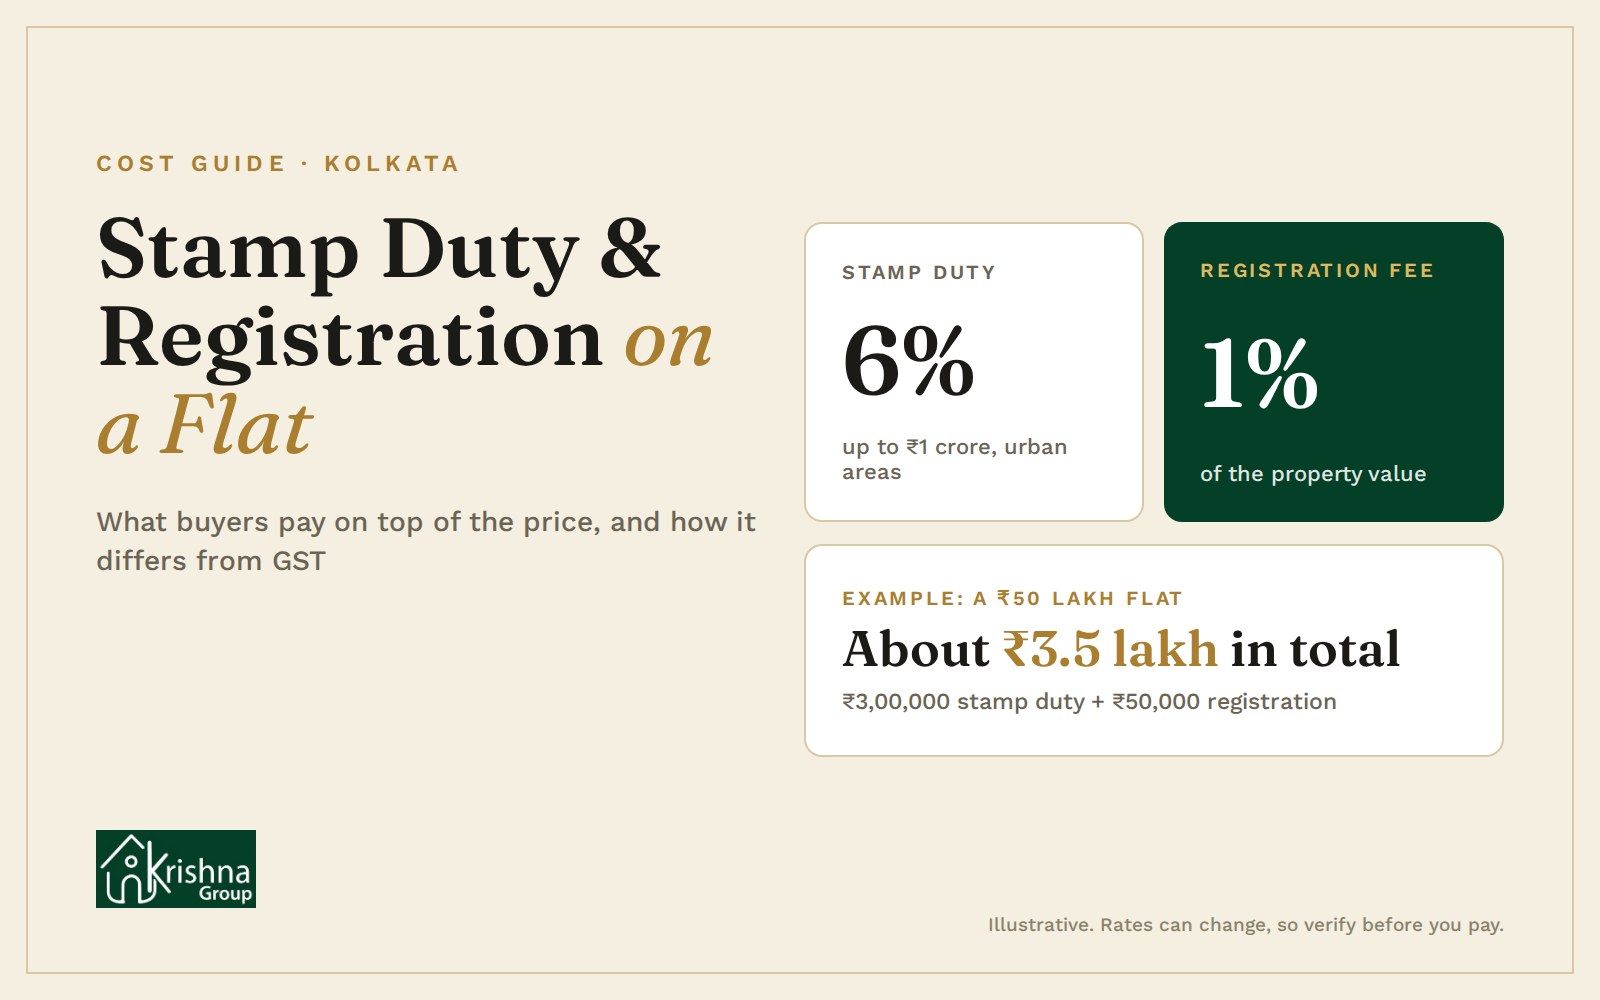
The part of the price the lender does not finance is your down payment. On top of that, stamp duty and registration charges are not included in the loan under RBI guidelines, so you pay them from your own funds. At the urban rate of about 7% in total, here is the cash you need before the first EMI: See how the registry works in our guide to flat registry charges and steps.
| Flat price | Max loan share | Max loan | Down payment | Stamp duty and registration (about 7%) | Cash needed upfront |
|---|---|---|---|---|---|
₹30 lakh | 90% | ₹27,00,000 | ₹3,00,000 | ₹2,10,000 | ₹5,10,000 |
₹40 lakh | 80% | ₹32,00,000 | ₹8,00,000 | ₹2,80,000 | ₹10,80,000 |
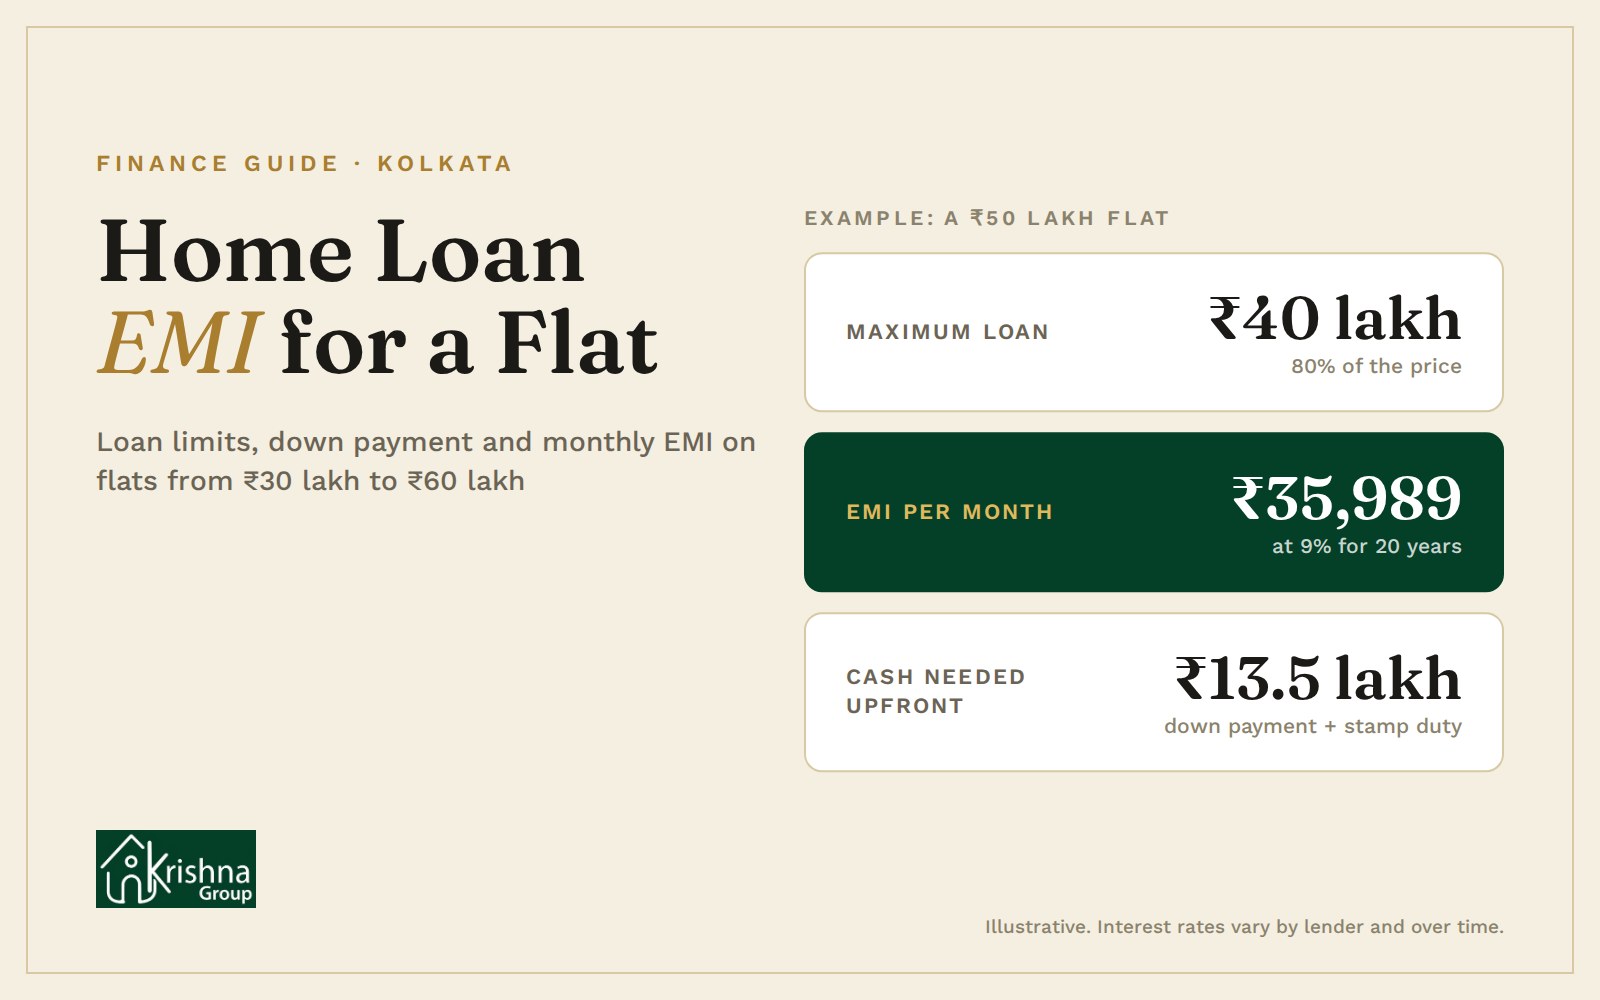
₹50 lakh | 80% | ₹40,00,000 | ₹10,00,000 | ₹3,50,000 | ₹13,50,000 |
₹60 lakh | 80% | ₹48,00,000 | ₹12,00,000 | ₹4,20,000 | ₹16,20,000 |
Illustrative, assuming the maximum loan. See our guide to stamp duty and registration charges in Kolkata for how the 7% is worked out. If the flat is still under construction, GST is extra, which we explain in our guide to ready-to-move flats and no GST.
EMI on a home loan for flats of ₹30 lakh to ₹60 lakh
Your EMI depends on the loan amount, the interest rate and the term. Home loan rates differ between lenders and change over time, so these examples use three illustrative rates over 20 years. They are not offers:
| Flat price (maximum loan) | EMI at 8% | EMI at 9% | EMI at 10% |
|---|---|---|---|
₹30 lakh (loan ₹27,00,000) | ₹22,584 | ₹24,293 | ₹26,056 |
₹40 lakh (loan ₹32,00,000) | ₹26,766 | ₹28,791 | ₹30,881 |
₹50 lakh (loan ₹40,00,000) | ₹33,458 | ₹35,989 | ₹38,601 |
₹60 lakh (loan ₹48,00,000) | ₹40,149 | ₹43,187 | ₹46,321 |
Monthly EMI on the maximum loan over 20 years. Calculated with the standard EMI formula; your lender’s figure may differ slightly with its own method and fees.
For example, a ₹40 lakh loan over 20 years costs about ₹33,458 a month at 8%, ₹35,989 at 9% and ₹38,601 at 10%. A one-point change in the rate moves the EMI by roughly ₹2,500 to ₹2,600 on that loan, so it is worth comparing lenders before you choose.
Longer term, lower EMI, more interest
You can lower your EMI by choosing a longer term, but you pay much more interest overall. Here is a ₹40 lakh loan at 9%:
| Loan term | EMI per month | Total interest paid | Total repaid |
|---|---|---|---|
15 years | ₹40,571 | ₹33,02,719 | ₹73,02,719 |
20 years | ₹35,989 | ₹46,37,369 | ₹86,37,369 |
25 years | ₹33,568 | ₹60,70,356 | ₹1,00,70,356 |
30 years | ₹32,185 | ₹75,86,566 | ₹1,15,86,566 |
Illustrative, at 9%. Many borrowers pick a term that keeps the EMI comfortable and then prepay when they can, if their lender allows it without a penalty.
When do EMIs start: ready to move or under construction?
With a ready-to-move flat, the loan is usually released in full and your EMIs begin soon after, but you can inspect the flat, move in and avoid GST. With an under-construction flat, the loan is usually paid out in stages as the building progresses, and you generally pay interest only on the amount released until possession, often called pre-EMI. You may also be paying rent in the meantime. Read our comparison of renting vs buying in Kestopur and our guide to ready-to-move flats with no GST to weigh the two.
What lenders look at
- Your income and existing loans: lenders check that you can comfortably afford the EMI alongside your current commitments.
- Your credit history: a strong repayment record can help you get a better rate.
- The property: clear title, sanctioned plans and, for completed flats, the completion certificate. Where a project is RERA-registered, lenders may also check that. See documents to check before buying a flat in Kolkata.
Have the documents reviewed before you commit. Our guide to the 10 mistakes to avoid when investing in Kolkata real estate explains the checks, including why you should never stretch your budget.
Krishna Group flats: loan and EMI at starting prices
Here is what the maximum loan and EMI look like at some starting prices across Krishna Group’s Kestopur developments, assuming 9% over 20 years:
| Flat | Starting price | Maximum loan | EMI at 9%, 20 years |
|---|---|---|---|
Krishna Lakeview 1 BHK | ₹26 lakh | ₹23,40,000 | ₹21,054 |
Krishna Heights 2 BHK | ₹32 lakh | ₹28,80,000 | ₹25,912 |
Krishna Paradise 2 BHK | ₹45 lakh | ₹36,00,000 | ₹32,390 |
Krishna Paradise 3 BHK | ₹50 lakh | ₹40,00,000 | ₹35,989 |
Krishna Lakeview 3 BHK | ₹52 lakh | ₹41,60,000 | ₹37,429 |
Starting prices are for the lowest-priced available unit, and the figures assume the maximum loan. Your own eligibility, rate and term will differ.
Krishna Group can connect you with home loan partners; ask our team. To see what each budget buys, read our guides to flats for sale in Kestopur, flats in Kolkata within 50 lakhs, 2 BHK flats in Kestopur and 3 BHK flats in Kestopur. For a first home under 30 lakh, see our guide to 1 BHK flats in Kestopur under ₹30 lakh, which also covers the PMAY interest subsidy.
Where to go next
Before you apply, work out your complete budget, including the stamp duty and registration charges and the locality you want to live in. For more buying advice, read our real estate tips for home buyers and smart real estate tips.
Frequently asked questions
How much home loan can I get on a flat in Kolkata?
Lenders can finance up to 90% of the property value for loans up to 30 lakh rupees, and up to 80% for loans between 30 and 75 lakh rupees. Your actual loan depends on your income, existing loans and credit history.
What is the EMI on a 40 lakh rupee home loan?
Over 20 years it is about 33,458 rupees a month at 8%, 35,989 at 9% and 38,601 at 10%. Your lender's rate and method will decide the exact figure.
Are stamp duty and registration included in the home loan?
No. Under RBI guidelines these costs are not included when the loan amount is calculated, so you pay them from your own funds along with the down payment.
What is the maximum tenure for a home loan?
Up to 30 years under RBI guidelines. A longer term lowers the EMI but increases the total interest you pay.
Does a ready-to-move flat cost less in GST?
A ready-to-move flat with a completion certificate issued before the sale does not attract GST, while an under-construction flat usually does. Stamp duty and registration apply to both.
Can Krishna Group help with a home loan?
Krishna Group can connect you with home loan partners. Call +91 91644 89774 or use the contact page to ask our team.
See a Krishna Group home in Kestopur
Call +91 91644 89774 or book a site visit to see the flats for yourself.
Krishna Group has been building homes in Kolkata since 1988 and has completed 40+ projects. Our five current developments – Krishna Paradise, Krishna Kamdhenu, Krishna Shivangan, Krishna Lakeview and Krishna Heights – are all in Kestopur.